Property developers in Hong Kong are feeling the squeeze. New World Development, one of the city's most prominent real estate families, just took a major step to handle its mounting pressures by securing acceptance from the Shanghai Stock Exchange for a massive commercial real estate investment trust spin-off.
The move involves carving out its crown jewels on Huaihai Road Central in Shanghai. If you have been tracking how traditional property giants are scrambling to raise cash and recycle capital, this development highlights the intense pressure developers face right now. Let us break down what is actually happening with the NWD C-REIT and why it matters.
Breaking Down the Shanghai K11 Spin-Off Deal
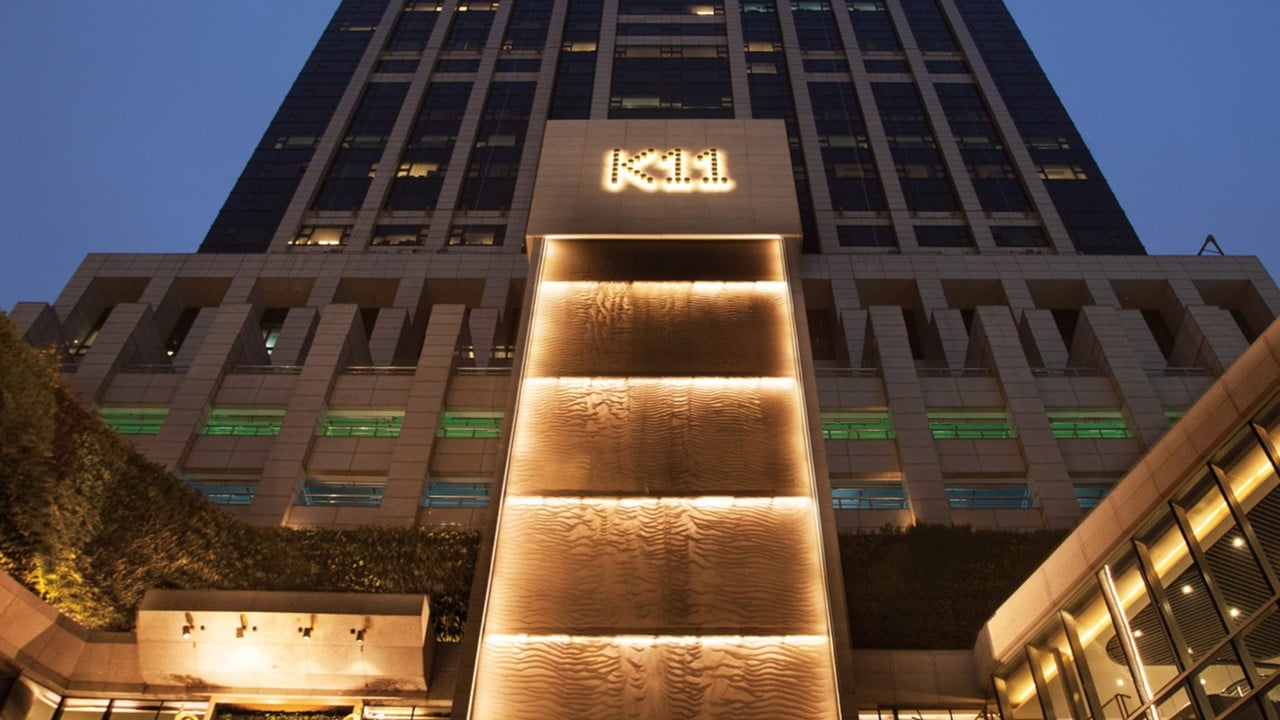
The transaction centers on the Shanghai Hong Kong New World Tower. That massive mixed-use complex houses the Shanghai K11 Art Mall and the Shanghai K11 ATELIER New World Tower office space. Together, these properties span roughly 130,384 square metres, or about 1.4 million square feet, sitting right in the core of Shanghai's Huangpu district.
Here is how the financial mechanics shake out based on corporate filings:
- The expected offering size for the NWD C-REIT sits at approximately 3.82 billion yuan, translating to roughly US$570 million.
- New World plans to sell the holding company of the towers to the newly listed REIT for 4.01 billion yuan.
- The developer will subscribe to at least 20 percent of the total REIT units, committing roughly 764 million yuan or letting external investors take the remaining slice.
- Net proceeds heading back to New World are projected at around 3.24 billion yuan, which management intends to channel directly into loan repayment and general corporate purposes.
By moving these assets into a public vehicle, New World shifts toward an asset-light model. They will retain management duties, meaning the K11 brand stays firmly stamped on the properties, but they unlock vital liquidity without losing operational ties.
Why This Strategic Pivot Was Necessary
Let us be honest about market conditions. New World Development has spent the past few years dealing with intense scrutiny over its heavy debt load compared to its regional peers. Tight credit markets, high borrowing costs, and a sluggish property climate across both Hong Kong and mainland China have forced developers to rethink how they hold assets.
In the past, holding trophy commercial real estate indefinitely was the ultimate status symbol for family-run conglomerates. Today, carrying those capital-heavy assets on the balance sheet is a liability.
CEO Echo Huang pointed out that the creation of this REIT provides access to entirely new forms of institutional and retail capital within the mainland market. Instead of letting prime retail and office space tie up billions in equity, the company converts bricks and mortar into liquid financial instruments.
Furthermore, controlling shareholder Chow Tai Fook Enterprises backed the plan with an irrevocable undertaking to vote in favour of the restructuring if an extraordinary general meeting is called. That internal alignment shows how unified the leadership is about getting debt under control.
What Developers and Investors Can Learn From This Move
If you are watching commercial real estate trends, this case study offers a clear look at where the industry is heading.
Traditional bank loans are no longer the easiest or cheapest route for capital-intensive firms. Public commercial REIT regimes on mainland exchanges offer an escape valve. Since consumer infrastructure entered the mainland's public REIT pilot program, developers have gained a viable exit strategy to monetize mature, cash-generating retail properties.
Yet, execution is never simple. REIT pricing depends entirely on how the broader market perceives cash flow stability, retail foot traffic, and rental yields in prime shopping districts like Huaihai Middle Road. If tenancy rates drop or consumer spending softens further, unit distributions face downward pressure.
New World still has more work ahead. Additional K11-branded assets in cities like Hangzhou and Shanghai are slated for completion soon, and the company will likely look at similar monetization strategies for those properties once they mature.
Managing a massive real estate portfolio in a high-interest-rate environment requires aggressive capital recycling. Sitting on static assets is a luxury developers can no longer afford. Watch how the retail investors and institutional buyers respond when the NWD C-REIT officially lists. That reception will dictate whether other heavily indebted Hong Kong property firms rush to copy the playbook.